
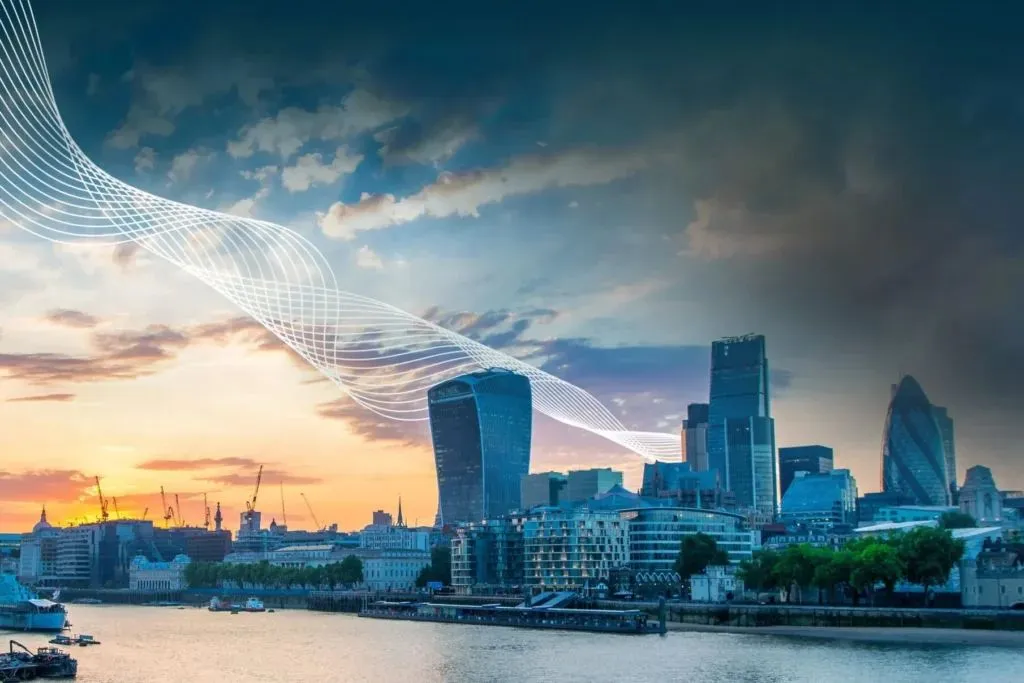
What are the current trends in commercial real estate capital allocation and investor sentiment, across London and the regions?
To understand the multi-level challenges shaping commercial property investors’ thinking and strategy, Property Week, in partnership with Freeths, has produced a report drawing on insights from clients, investors, industry specialists and Freeths’ specialists.
London
“For a lot of people, London feels less risky for longer term investments”
Daniel Abrahams, Real Estate Partner, Freeths
Daniel Abrahams
Despite Covid, interest rates, and geopolitical instability, the capital remains the number one single destination for commercial property investment in the UK. Nearly half of the £10.7bn invested in the sector in London in Q2 2026 came from overseas investors.
Activity in the office market in particular is picking up after a sustained period of retrenchment. But it remains a tale of two markets, with grade A stock in prime locations significantly outperforming lower grade stock and less desirable locations.
High construction costs, interest rates and inflation remain serious concerns, if less of an issue than in many regional markets. The UK’s deteriorating public finances, and uncertainty about potential new government policies such as a land value tax, could also deter investors.
There remains plenty of capital to deploy in London, but dealflow is unlikely to accelerate until investor confidence, and with it momentum, returns to the market.
The regions
“Lender appetite is returning in the best performing regional cities”
Lucy Bradban, Partner, Freeths
The UK’s regional markets account for the majority of capital invested in commercial property in the UK – around two-thirds annually for the past five years.
Lucy Bradban
Investors are drawn to regional cities principally by the prospect of keener value, smaller deal sizes and less competition amongst bidders.
The regional watchword in 2026 is caution. There is nervousness about liquidity, and the impact of voids.
Lower-risk market-ready assets are more popular than ‘fixer-uppers’ which take longer to make a return.
Construction and funding costs threaten the viability of ground-up development across most sectors. But the lack of new stock is making office refurbs, for example, more attractive in cities such as Bristol, Leeds and Manchester.
Out of town retail and commercial opportunities are a bright spot, offering some of the highest predicted regional returns over the next five years.
Optimism that new PM Andy Burnham will prioritise economic growth in the regions is tempered by concerns that additional costs may be imposed in some sectors.
The investor view
“Fundraising is as hard now as it was in 2008, during the Global Financial Crisis”
Simon Ringer, Head of Property Funds, Bridges Fund Management
Simon Ringer
Commercial property investors are grappling with the impact of high levels of geopolitical and economic uncertainty on allocation decisions, and on returns.
As an investment class, commercial property faces rising competition from the likes of equities, gilts and commodities. There have been individual institutional exits from property, but institutional investors as a group still regard property assets as a key part of a balanced and diversified portfolio.
Taking an opportunistic approach to capital allocation allows investors the flexibility and agility required to succeed in uncertain times. As does focusing on resilient, demand-led opportunities where the fundamentals are strong – such as the living, low carbon I&L and healthcare sectors.
With wider uncertainty unlikely to settle, investors’ concern will continue to focus on the macro as much as the micro, particularly on factors that influence liquidity on exit.