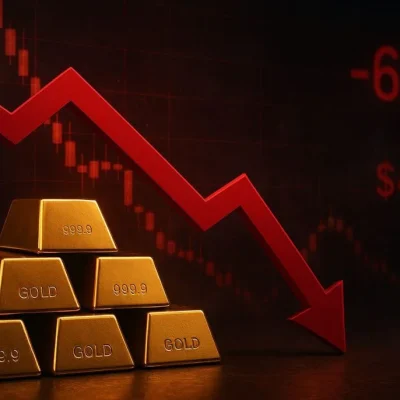

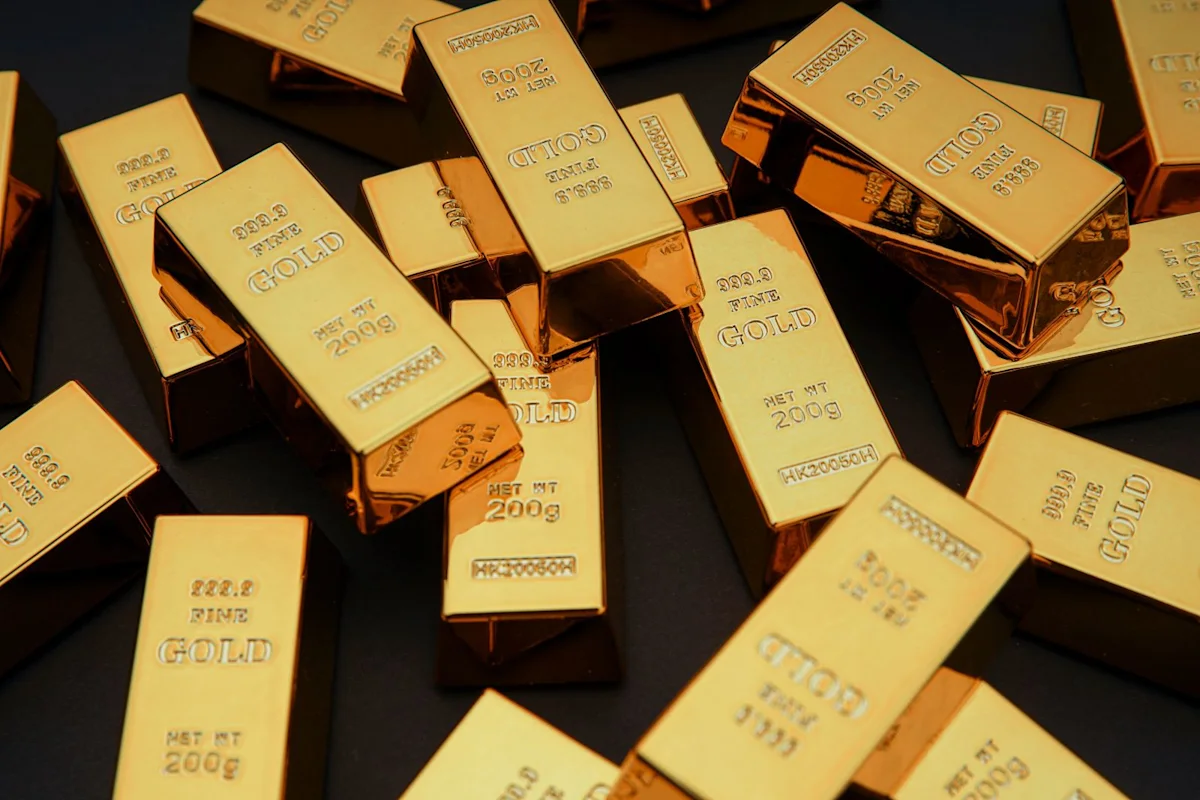

Gold (GCZ26) is the anti-inflation trade, the alternative currency, the asset to own when all is lost. At least that’s what Wall Street pundits have said for decades. I say, “that’s one of the worst charts I see right now. And I see a lot of charts.”

Surely silver (SLV) will buck the trend, right? Nope, that chart looks pretty risky too.
More News from Barchart

I have never viewed these two precious metals, or ETFs that track them, as safe havens. I have capitalized on their past price rises by owning funds and call options. But as we enter October, I’m much more likely to find my way into them via inverse ETFs, such as the ProShares UltraShort Gold ETF (GLL) or the ProShares UltraShort Silver ETF (ZSL). Because while every time inflation ticks up, geopolitical tensions flare, or federal deficits explode, the narrative is predictable: buy hard assets to protect your wealth.
As an active risk manager, I look at GLD and SLV today and see a way to bypass short-term Treasury bills that pay 4.5% and 5-year Treasuries that yield over 5% to instead hold non-yielding, highly volatile commodities. And there’s NO WAY I’m doing that with charts that look like these. If I had to break the tie for which of the two is worse, it would be gold. But that’s not saying much. This pair might as well be tin and lead.
Silver: Just a Dressed Up Industrial Metal
Silver is a wild card. It always has been. And fresh off suckering in true believers with the allure of quick upside, it now looks more like it is setting up for a repeat of its post-2011 dive that eroded more than 75% of SLV’s value.

Gold bugs like to promote silver as “gold on steroids,” but the market treats it far more like an industrial base metal. Like copper (HGZ26), or the aforementioned lead. It has some tangible applications, certainly more than gold has. But this is just another commodity that investors, retail and otherwise, use as a trading tool.
Over 50% of global silver demand comes from industrial applications: electronics, solar panels, and manufacturing. However, when economic growth slows or manufacturing contracts, silver gets hit with a double whammy. Industrial demand collapses, as declining manufacturing activity pulls down silver’s own demand. And it becomes another high volatility asset. Silver’s annual price volatility rivals speculative tech stocks, routinely suffering 20%-35% drawdowns during market pullbacks.