
Direct Ownership vs a Pooled Vehicle
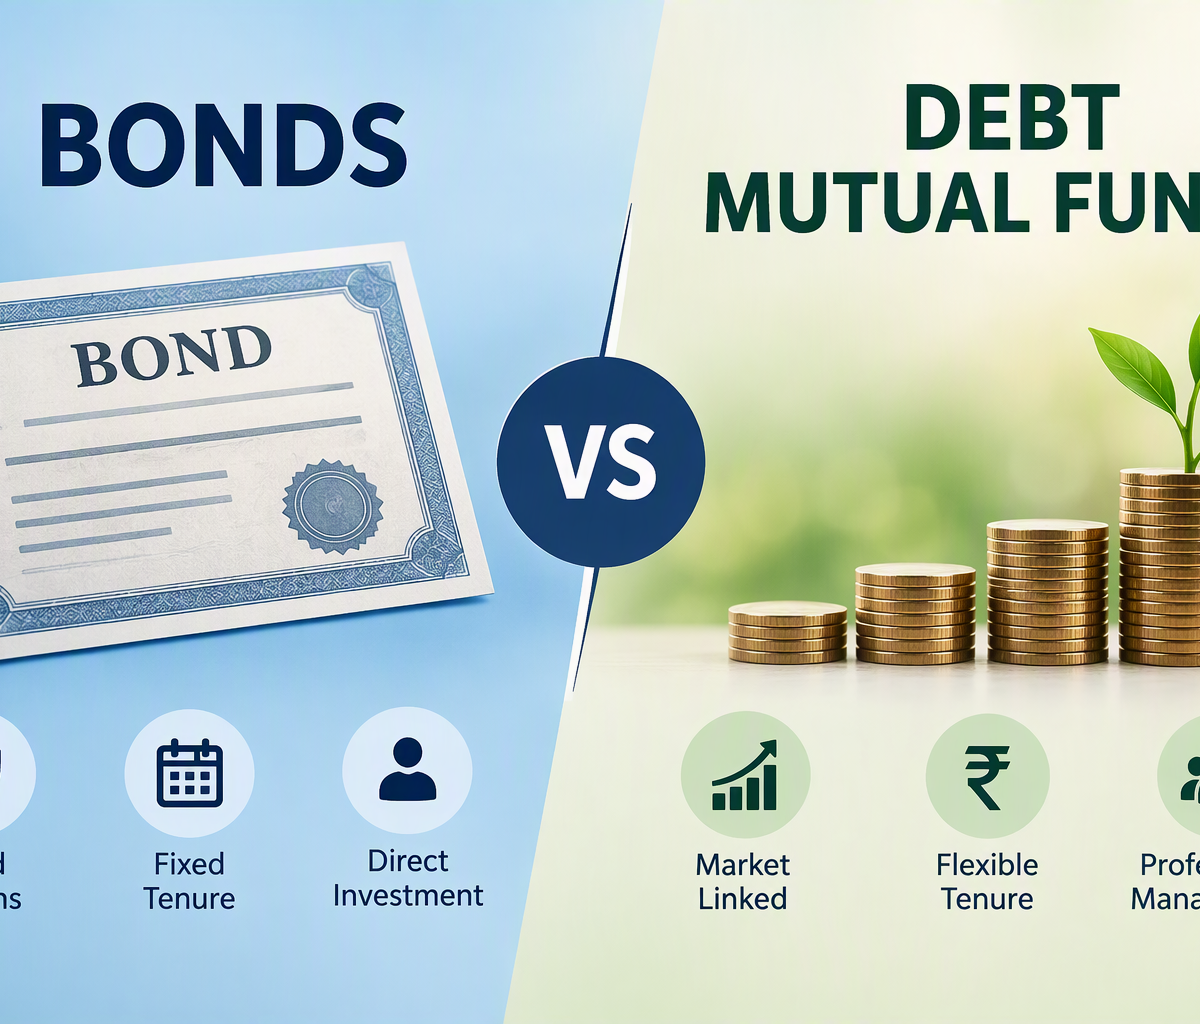
When you buy a bond directly, you own a specific instrument issued by a specific company or government entity, with a defined coupon, maturity date, and (usually) a credit rating. A debt mutual fund, on the other hand, pools money from many investors, and a fund manager allocates it across a basket of bonds, government securities, and money market instruments, based on the fund’s stated investment mandate.
Liquidity
Debt mutual funds are generally easier to exit; most open-ended funds allow you to redeem units on any business day, with the amount credited within a day or two, subject to any exit load. Direct bonds, especially unlisted or thinly traded ones, can be harder to sell anytime before maturity; even listed bonds may have limited daily trading volumes, which can affect the price you get if you need to exit early.
Cost
Debt mutual funds charge an expense ratio, an annual fee covering fund management and administrative costs, which is deducted from the fund’s returns. Direct bonds don’t carry a recurring expense ratio, but you may pay brokerage or platform charges at the time of purchase, and bid-ask spreads can affect pricing, particularly for less liquid bonds.
Control Over What You Own
With direct bonds, you choose the specific issuer, coupon, and maturity, and you know exactly what you’re holding until it matures or you sell it. With a debt fund, the fund manager decides the underlying holdings within the fund’s mandate, and the portfolio composition can change over time as the manager adjusts to market conditions so your actual credit and duration exposure can shift without any action on your part.
Taxation
Tax treatment differs meaningfully between the two, and this is an area where rules have changed in recent years. Most debt mutual funds (those investing predominantly in debt rather than equity) are now taxed at the investor’s income tax slab rate on redemption, regardless of the holding period, following changes introduced in the Finance Act, 2023. Direct bonds, by contrast, may attract different tax treatment depending on the holding period and whether the gain is treated as capital gains versus interest income. Because these rules can change with each Union Budget, confirm the current provisions or check with a tax advisor before assuming a particular treatment applies to your specific bond or fund.
Diversification
A single bond concentrates your credit risk in one issuer. A debt fund typically spreads investments across multiple issuers and instrument types, which can reduce the impact of any single issuer running into trouble, though it doesn’t eliminate the fund’s overall exposure to interest rate movements or a broad credit downturn.
Which Might Suit You?
If you want a hands-off approach, daily liquidity, and diversification across issuers, a debt mutual fund may be the more convenient route. If you prefer to select specific issuers and lock in a defined coupon and maturity, and you’re comfortable holding until maturity, direct bonds can offer more clarity on what you’ll earn and when.
Frequently Asked Questions
Which option has lower risk, i.e., bonds or debt mutual funds?
It depends on the specific bond or fund. A single high-rated bond can carry lower credit risk than a fund holding lower-rated paper, and vice versa; the instrument’s own credit quality and the fund’s mandate matter more than the broad category.
Can I lose money in a debt mutual fund?
Yes. Debt fund NAVs can fall due to interest rate movements, credit rating downgrades of underlying holdings, or a default by an issuer the fund has invested in.
Do debt mutual funds get any indexation benefit now?
For most debt-oriented mutual funds (with equity allocation below the threshold defined under current tax law), indexation benefit was removed for units acquired on or after 1 April 2023, and gains are taxed at slab rates confirm the latest position with a tax advisor, since this area has seen recent changes.
Is it possible to hold both bonds and debt mutual funds in the same portfolio?
Yes, many investors use both direct bonds for a defined, targeted allocation and debt funds for the more liquid, diversified portion of their fixed-income holdings.