
Khalifa Aldhaheri is the Vice Chairman of Vertix Holdings.

Every real estate downturn gets blamed on the same culprit after the fact: The market turned, rents softened, capitalization rates widened and asset values fell. That explanation is comforting because it treats the damage as something that arrived from outside, an event nobody could have priced for.
In my years structuring and overseeing large commercial and development platforms, I have come to believe that story is usually incomplete, and sometimes it is simply wrong. The asset didn’t always fail first. The debt schedule did.
A Date, Not A Downturn
A maturity wall is not a market event. It is a date. It is the point where a loan originated five, seven or 10 years earlier comes due regardless of what has happened to occupancy, rental income or the broader economy in the meantime.
The Federal Reserve’s May 2026 Financial Stability Report puts this plainly: A large volume of commercial real estate debt is scheduled to mature over the coming year, and lenders’ willingness to extend or modify those loans, the mechanism that has quietly absorbed much of this risk so far, may be increasingly limited going forward.
That is a central bank, not a headline writer, describing the exposure. It has nothing to do with whether any individual asset is performing. It is simply what was promised, on paper, years before anyone knew what conditions would look like when the bill arrived.
What Underwriting Actually Bets On
The distinction matters because it changes where the discipline needs to sit.
If risk is purely a market phenomenon, the response is to time entries and exits well and hope the cycle cooperates. If risk is structural, sitting in the shape of the debt itself, the response has to happen at underwriting, long before the market has any say in the outcome.
A loan originated with a five-year term against a 10-year hold thesis is not simply a financing decision. It is a bet that refinancing conditions in year five will resemble year zero. That bet has broken more platforms than bad tenants ever have.
The Towers That Proved The Point
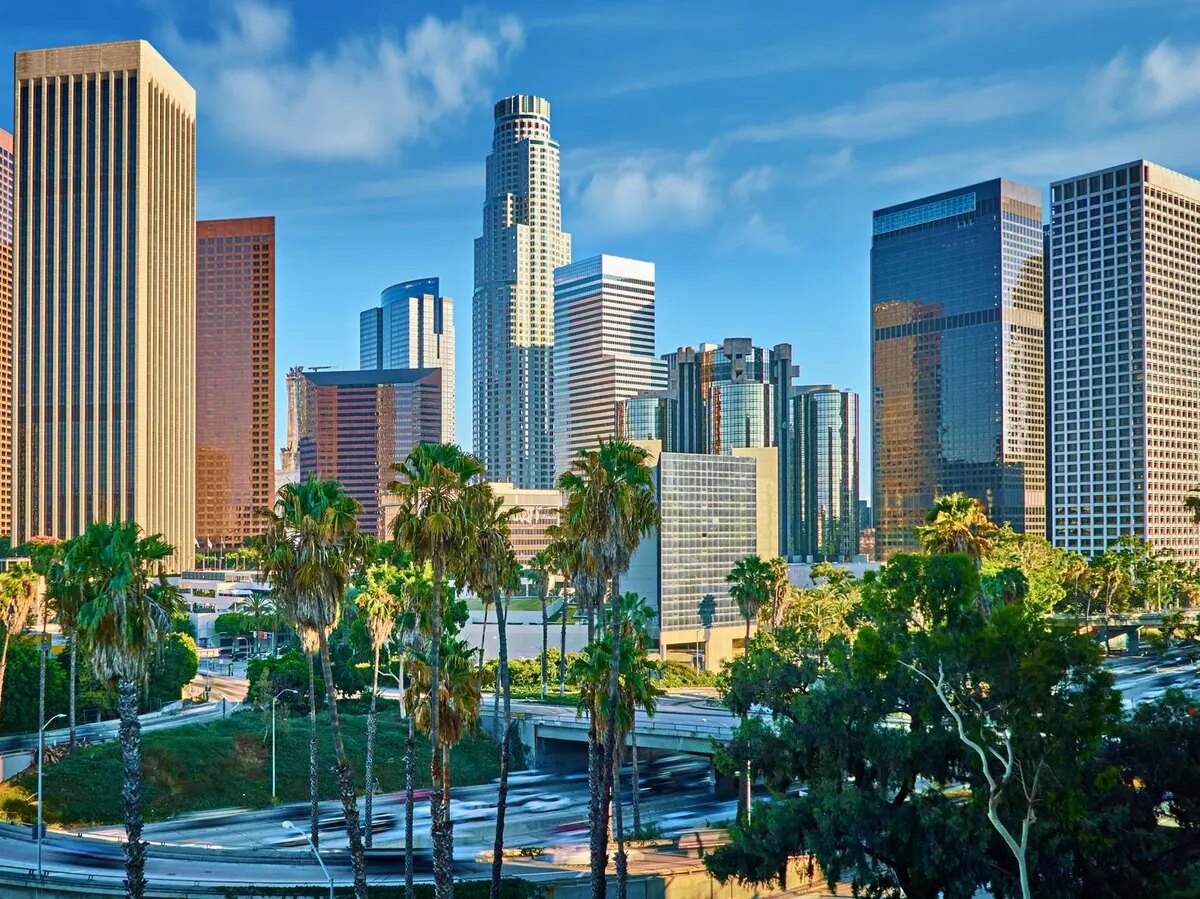
The clearest recent illustration sits in downtown Los Angeles. In February 2023, Brookfield’s real estate investment arm defaulted on roughly $784 million in loans tied to two office towers, the Gas Company Tower and 777 Tower. The buildings themselves were not empty shells; they were established assets with real tenants. What forced the decision was the collision between loans coming due and a refinancing environment that no longer resembled the one in which those loans were written.
This was not a story about a market collapsing overnight. It was a story about a calendar catching up to a capital structure built for a different set of assumptions.
The Stress Test Everyone Skips
What I find more interesting than the default itself is how rarely this gets discussed as an underwriting failure rather than a market failure.
Boards and investment committees spend enormous energy stress-testing occupancy assumptions, rent growth and exit capitalization rates. Far less energy goes into stress-testing the maturity schedule against those same assumptions, asking a simpler question: If refinancing terms in years five or seven are meaningfully worse than they are today, does this structure survive, or does it force a decision onto someone else’s timeline?
Built Not To Need A Forecast
The platforms that come through these periods intact are rarely the ones that guessed the cycle correctly. They are the ones that staggered maturities across years rather than concentrating them, diversified lending relationships so no single institution’s appetite could dictate an outcome, and underwrote leverage against a range of refinancing environments rather than the most favorable one available at closing.
None of that requires forecasting skill. It requires treating the debt schedule as a design decision rather than a by-product of whatever terms happened to be available when the deal needed to close.
The Variable To Watch
This is, admittedly, a less exciting explanation than blaming the market. It offers no external villain and no cycle to simply wait out. It puts the responsibility back on decisions made at origination, years before anyone could see the wall coming. But that is precisely why it deserves more attention than it gets.
Markets are, by nature, unpredictable. Calendars are not. A maturity date is the one variable in commercial real estate that is known in full on day one, and it is the one most consistently ignored until it arrives.
The discipline that protects a portfolio is rarely the discipline that predicts the future. It is the discipline that refuses to build a capital structure that needs to.
The information provided here is not investment, tax or financial advice. You should consult with a licensed professional for advice concerning your specific situation.
Forbes Finance Council is an invitation-only organization for executives in successful accounting, financial planning and wealth management firms. Do I qualify?