
In the Nikkei 225 futures market, a state of high volatility has continued since mid-October.
As of October 30, the ATM implied volatility (IV) is 32.33%.
Meanwhile, the realized volatility forecast until SQ based on statistical models is 27.66%.
There is a 4.67-point difference between the two, and the options market is pricing in larger price fluctuations than the statistical model’s forecast.
However, high IV and options being overpriced are not necessarily the same thing.
In this report, we will organize the trends of realized volatility (RV), future forecasts by the HAR model, and ATM IV to analyze the market environment leading up to the November SQ.
1. Key data as of October 30
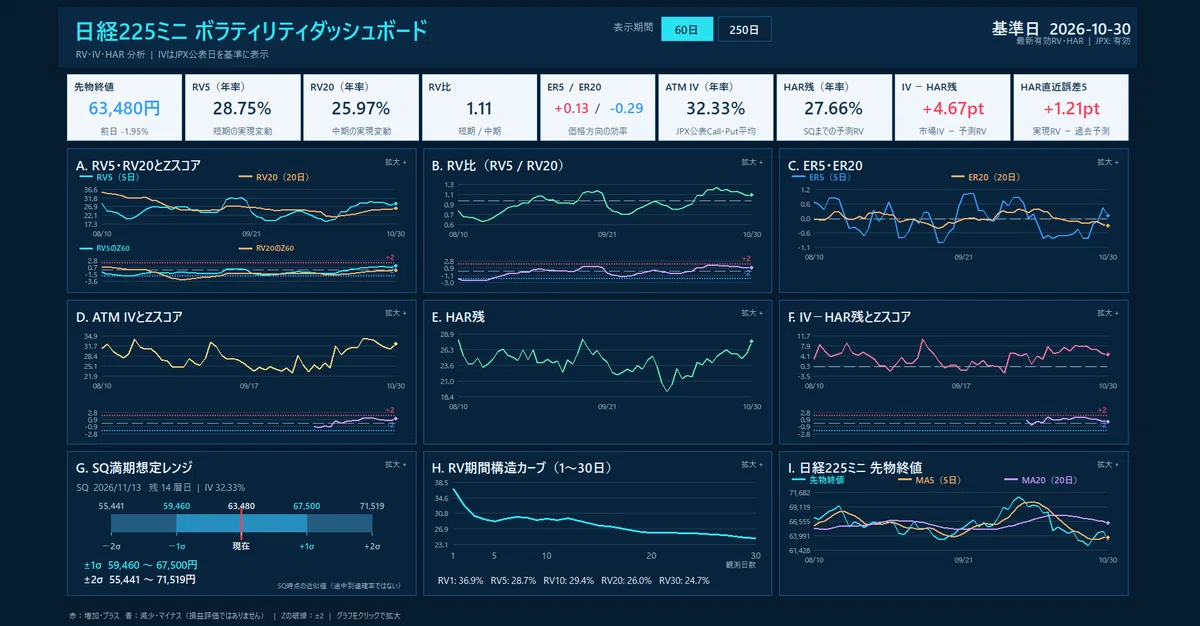
* RV, HAR, and IV are all annualized values. The analysis reference date is October 30, 2026.
2. Realized volatility remains high
The current RV5 is 28.75% and RV20 is 25.97%.
The fluctuations over the last 5 days exceed those of the past 20 days, indicating that the state of high short-term volatility continues.
Looking at the chart for the last 60 trading days, RV5, which had stabilized from late September to early October, rose significantly after mid-October.
Since then, the gap between RV5 and RV20 has narrowed slightly.
What we want to focus on here is the point that even if the RV ratio begins to decline, the RV itself remains high.
Furthermore, RV1 is approximately 36.9%, which is significantly higher than the RV5 of 28.75%.
This indicates that the fluctuation over the most recent day was large, and it is still too early to judge the convergence of volatility.
If the decline in RV1 continues, it could lead to a stabilization of short-term volatility. On the other hand, if large daily fluctuations continue, the high-volatility environment will be reflected in medium-term indicators such as RV20.
3. What is the direction of prices?
To confirm the direction of prices, we will look at the ER (Efficiency Ratio).
The current ER5 is +0.13 and ER20 is -0.29.
ER is an indicator that shows how efficiently a price has moved in one direction over a certain period, ranging from -1 to +1.
Since ER20 is negative, a bias toward the downside remains in the medium term.
On the other hand, ER5 is close to zero, indicating that a clear direction in recent price movements has weakened.
In other words, the current market can be considered one where a medium-term downward trend persists while short-term gains and losses are mixed.
In such a phase, it is necessary to be cautious not only about the continuation of a sharp decline but also about the possibility of a significant rebound.
4. How does the HAR model predict future volatility?
HAR is a statistical model that uses past realized volatility to predict future volatility.
As of October 30, the HAR residual is 27.66%.
Looking at recent trends, the HAR residual declined in mid-October before rising again toward the end of October.
This means that the statistical model is raising the expected level of future fluctuations.
Additionally, in the verification of the recent 5-day forecast, the actual RV exceeded the HAR forecast at that time by 1.21 points.
However, this is a verification result of a 5-day forecast made in the past and is not the prediction error of the current HAR residual of 27.66%.
In past periods of sharp fluctuations, HAR has sometimes significantly underestimated future RV.
Therefore, it is necessary to consider not only the central HAR forecast but also the risk that the realized RV will exceed the forecast.
5. Are options expensive or cheap?
The current ATM IV is 32.33%, and the HAR residual is 27.66%.
IV – HAR residual = +4.67 points
The market IV is 4.67 points higher than the future RV predicted by the statistical model.
This difference suggests that the option price may include a premium for future fluctuation risk.
However, in recent trends, the divergence between IV and the HAR residual has narrowed from the high levels seen in mid-October.
This is an important point.
Even if IV itself is high, if the future RV forecast by HAR is also rising, the relative overvaluation does not necessarily expand.
Currently, the option market is pricing in high volatility, while statistical models are also predicting high future fluctuations.
Therefore, one cannot judge that options are overvalued simply because IV exceeds 32%.
Note that this ATM IV is a reference value published by JPX and does not directly represent actual tradable prices or the IV skew for each strike price.
Also, the divergence between IV and HAR does not directly imply the expected profit of selling options.
6. Assumed Price Range for November SQ
The November SQ is November 13, 2026.
The remaining period from October 30 to the SQ is 14 calendar days.
Using the current futures price of 63,480 yen and an ATM IV of 32.33%, calculating the assumed fluctuation range at the time of SQ using the square root rule yields the following.
Assumed Range Lower Limit Upper Limit ±1σ 59,460 yen 67,500 yen ±2σ 55,441 yen 71,519 yen
In a simple approximation using a normal distribution, ±1σ corresponds to approximately 68% and ±2σ to approximately 95% of the range.
However, these are model-based guidelines and do not guarantee that the actual price will fall within that range.
What requires special attention is the fact that the price range at the time of SQ and the probability of reaching each price during the period leading up to the SQ are different.
This difference is important in option position management.
7. Three Scenarios for November SQ
Regarding future volatility, we assume the following three developments.
Scenario 1: Volatility Convergence
A development where RV1 declines and RV5 also gradually settles down.
As a result, the RV ratio and HAR forecast may decline, and there may be downward pressure on market IV as well.
However, the decline in RV and the decline in IV do not necessarily occur at the same time.
Scenario 2: Continuation of High Volatility
This is a scenario where RV5 remains elevated, and RV20 and HAR forecasts also maintain high levels.
Based on current data, I believe we must continue to be cautious about this possibility.
If short-term rises and falls intersect, high RV can persist even if the price direction is not clear.
Scenario 3: Re-expansion of Volatility
This is a scenario where RV1 surges due to a new significant decline or sharp rebound, and IV also rises again.
In this case, the HAR model’s forecast may not keep up with actual fluctuations, potentially leading to increased under-forecasting.
It is necessary to check the trends of short-term RV and IV more carefully.
8. Summary: Currently in a Phase of Assessing the Convergence of High Volatility
As of October 30, the market continues to experience high realized volatility.
Although the RV ratio has declined slightly from its recent high level, RV1 remains high, and the future forecast by HAR is also rising.
Meanwhile, ATM IV is at a high level of 32.33%, but the difference from the HAR residual has narrowed to +4.67 points.
Based on this, I evaluate the current situation as follows:
“While the state of high volatility continues, there are signs of a slowdown in its expansion rate. However, the statistical model’s future forecast is rising, and we are not yet at a stage where we can confirm a full-scale convergence.”
Going forward, I would like to pay particular attention to whether the decline in RV1 continues, whether the difference between RV5 and RV20 narrows further, and in which direction the HAR residual and ATM IV change.
When evaluating whether options are expensive or cheap, I believe it is important to continuously observe not only the absolute level of IV but also its relationship with future realized volatility forecasts.
About the analysis data
This article is based on realized volatility calculated from 5-minute Nikkei 225 mini futures, forecast values from the HAR model, and ATM IV published by JPX.
The analysis reference date is the end of the trading day on October 30, 2026. Data during the November 2 trading day is not treated as confirmed daily RV.
This article is intended for the analysis of market data and does not recommend any specific trading.