
[September 22, 2026 Market Overview]
Today’s global markets were characterized by the contrast between a sharp plunge in oil prices following the partial resumption of a Saudi Arabian pipeline and a proposal to reopen the Strait of Hormuz and Nasdaq 100 futures hitting an all-time high. While the U.S. 10-year Treasury yield remained range-bound around 4.95%, buying has spread to the stock and precious metals markets.
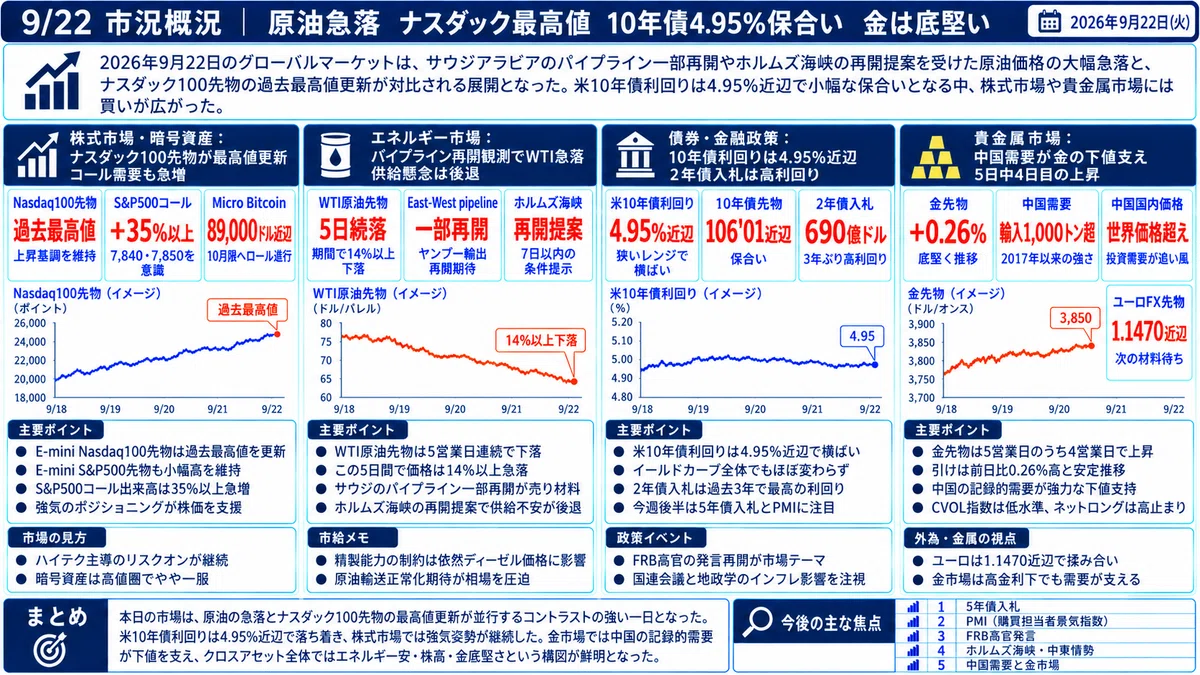
1. Stock Market & Crypto: Nasdaq 100 futures hit all-time high, S&P 500 call volume surges over 35%
-
Major indices hit record highs: E-mini Nasdaq 100 futures continued their recent strong trend and hit an all-time high. E-mini S&P 500 futures also maintained their upward trend from the start of the week, trading slightly higher[1].
-
Bullish stance in the options market: Bullish positioning is prominent in the equity options market, with S&P 500 call option volume surging over 35% as traders target the 7,840 and 7,850 call strikes.
-
Cryptocurrency market: Micro Bitcoin futures showed signs of stabilization after recent gains, but as rollover to the October contract progresses ahead of Friday’s expiration (SQ), they are facing volume resistance near $89,000.
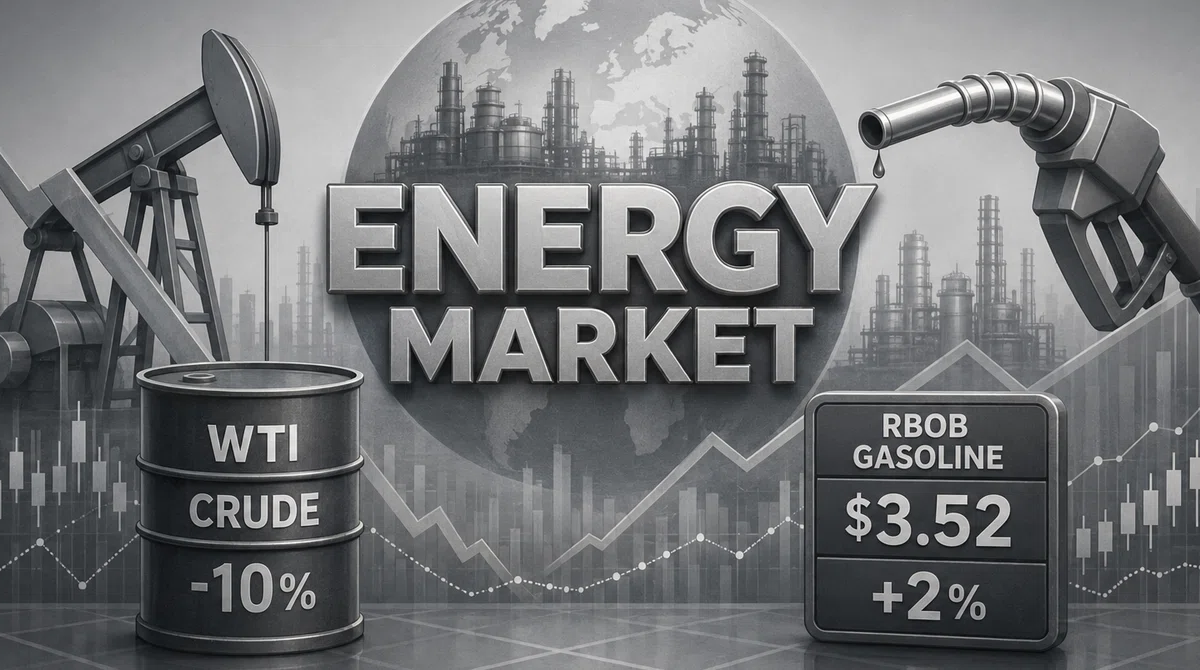
2. Energy Market: WTI crude oil futures fall for 5th consecutive day (down over 14%) on positive news of easing geopolitical risk
-
Consecutive sharp drops in oil prices: WTI crude oil futures faced increased selling pressure and fell for 5 consecutive trading days. Over this period, prices have plunged more than 14%[2].
-
Pipeline resumption and Strait of Hormuz proposal: The Saudi Aramco “East-West Pipeline,” which had been disrupted by a drone attack on September 13, has resumed operations at reduced capacity, and the expected resumption of exports from Yanbu acted as a selling factor[2]. Furthermore, a proposal from the Iranian side to reopen the Strait of Hormuz within 7 days if U.S. military conditions are met has raised hopes that the 7-month-long operational disruption will be eased.
-
Concerns over refined products: Despite signs of easing in crude oil transport, refining capacity issues resulting from the ongoing conflict continue to impact the prices of refined products such as diesel.
3. Bonds & Monetary Policy: 10-year yield flat around 4.95%, 2-year note auction sees highest yield in 3 years
-
Yields and range-bound trading: U.S. 10-year Treasury futures continue to consolidate within a narrow range at the 106’01 level, with the U.S. 10-year Treasury yield flat around 4.95%[3]. The yield curve as a whole remains largely unchanged.
-
Treasury auctions and economic indicators: The $69 billion 2-year Treasury note auction conducted by the U.S. Treasury was completed at the highest yield in the past three years. Auctions for 5-year notes and others, as well as the release of PMI (Purchasing Managers’ Index) data, are scheduled for later this week. Additionally, the impact of geopolitical discussions at the UN conference on inflation and monetary policy remarks by Fed officials following the FOMC remain of interest to the market.
4. Precious Metals Market: Strong Chinese demand supports the downside, gold futures rise for the 4th time in 5 days
-
Stable performance of gold: Although gold futures rose in 4 of the last 5 trading days, they ended the day with a relatively stable movement, up 0.26% from the previous day [4].
-
Inflation risk and bottoming out of Chinese demand: While tensions in the Middle East and disruptions in the Strait of Hormuz raise awareness of energy inflation risks and concerns that the Fed will maintain high interest rates, record demand from China is providing strong support for the floor [4].
-
China’s gold imports exceed 1,000 tons: China’s gold imports through August have surpassed 1,000 tons, exceeding the annual total for 2025 and showing the strongest demand since customs records began in 2017. This robust investment demand has pushed domestic Chinese prices above global levels, providing a tailwind for the gold market even after the Fed’s interest rate hikes.