The Morning Bull – US Market Morning Update Thursday, Oct, 22 2026
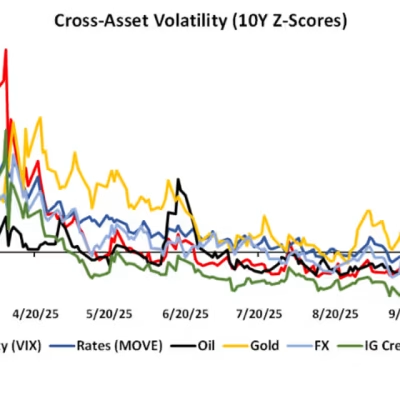
US stocks look set to open weaker, with futures pointing lower as investors react to a sharp upside surprise in UK inflation. The move is feeding a more cautious mood around global central bank policy.
UK CPI printed at 3.5% in September, with core inflation at 2.8%, both above recent trends and prior readings. These numbers have raised expectations that tight policy in major economies may persist longer than markets had been assuming.
Higher for longer policy thinking tends to pressure longer term bond yields, which directly affects borrowing costs for US households and companies. That can compress valuation multiples for growth heavy indices and complicate earnings plans for capital intensive businesses.
The key question now is whether upcoming US data breaks or confirms this stickier inflation story, particularly initial jobless claims today and PMIs on Friday. If US numbers echo the UK pattern, investors may need to reassess how much policy relief is realistically priced in.
Stocks to Watch Before the Opening Bell
Southwest Airlines (LUV)
Record Q3 2026 earnings from Southwest Airlines beat Wall Street expectations, supported by all time high unit revenues and strong overall operating revenues. The carrier also issued guidance for the current quarter and full year. Investors now have two dates to mark: the first Southwest Icon Lounge opens in 2027, and a Capital Markets Day is set for March 2, 2027.
Reliance (RS)
Reliance posted record Q3 2026 results, with net sales of US$5.21b and non GAAP diluted EPS of US$8.02, 120% higher year over year and ahead of analyst forecasts. The metals service center business expanded its share repurchase program to US$2.5b and declared a US$1.25 quarterly dividend. Management also issued Q4 EPS guidance of US$7.40 to US$7.60.
Teledyne Technologies (TDY)
Teledyne Technologies reported all time record quarterly sales, operating profit, and non GAAP diluted EPS for Q3 2026. The company also agreed to acquire Varex Imaging in a US$1.1b deal that is expected to close in early 2027. Strong cash flow supported US$224.6m of stock buybacks, indicating ongoing capital return alongside expansion in imaging hardware.
Top Movers
Skydance (SKYD) jumped 10.85% after John Malone flagged a potential US$8b to US$10b SpaceX investment and content partnership.
Zscaler (ZS) gained 7.84% as investors reacted to upbeat commentary on cybersecurity demand for securing AI agents and data.
Space Exploration Technologies (SPCX) climbed 7.79% following strong Q3 results and fresh Tesla merger talk that kept AI optimism elevated.
SKYD 1-Year Stock Price Chart
Top Losers
AT&T (T) fell 6.45% as investors reacted to mixed Q3 metrics and concerns around fiber pricing and Starlink competition.
Netflix (NFLX) declined 5.31% after weak Q4 guidance, ad revenue forecast cuts, layoffs, and a wave of analyst downgrades.
Expedia Group (EXPE) declined 5.03%.
T 1-Year Stock Price Chart
On The Radar
Wall Street faces a tight cluster of US data and mega cap earnings that all feed straight into views on growth, inflation, and the path of interest rates.
US Initial Jobless Claims, Thu 22 Oct, come with a prior reading of 199K and a consensus of 200K. Any figure meaningfully above that range would flag softer hiring conditions that typically ease pressure on future rate hikes and long term yields.
US S&P Global PMIs (manufacturing, services, composite), Fri 23 Oct, carry prior readings of 55.9, 58.8, and 58.4. Prints below those levels would point to cooler momentum that can temper expectations for aggressive policy tightening and help rate sensitive stocks.
Microsoft (MSFT) Q1 2027 results, Wed 28 Oct After Market, put the spotlight on cloud and AI related revenue and margins, which feed directly into how investors treat large cap tech as a growth anchor for the major US indices.
Alphabet Q3 2026 results, Wed 28 Oct, focus attention on ad related revenue and any commentary around search and YouTube spending trends, which matter for how investors value the broader online advertising ecosystem.
Fed Interest Rate Decision, Wed 28 Oct, keeps the policy rate referenced at 4% with consensus also at 4%. Any signal that borrowing costs will remain restrictive for longer would filter quickly into US bond yields, the dollar, and equity risk appetite.
Sector & Industry Watch
Energy & Oil and Gas: Tight oil backdrop supports pricing power
Energy and Oil and Gas are both modestly higher over the past week, building on strong year to date and 1 year gains. A larger than expected 3.06 million barrel draw in US crude inventories points to firm demand or constrained supply, which tends to support cash generation for producers and pipeline operators.
If you hold energy ETFs or integrated producers, the next weekly EIA inventory report is the key checkpoint for whether this tighter oil story is still intact.
Real Estate: Mortgage rate dip, housing demand still soft
Real Estate is up around 1.3% over the last seven days but weaker over 30 days, a pattern that fits brief rallies inside a tougher rate backdrop. The 30 year US mortgage rate just eased to 7.41%, yet mortgage applications fell for a seventh straight week, which tells you high borrowing costs are still chilling home purchases and refinancing.
For REIT and homebuilder investors, today’s US initial jobless claims near the 200K consensus matter because any move in Treasury yields from that data flows straight into property financing costs.
Tech & Semiconductors: AI buildout strong, funding questions grow
Tech is barely lower over 7 days while still well ahead year to date, and Semiconductors show a similar pattern, with a small weekly dip against very strong longer term returns. Recent headlines around Nvidia’s heavy AI infrastructure spend, CoreWeave’s new security framework, and crowded chip supply chains highlight how much demand ties back to financed AI data center projects.
If you own broad Tech or chip ETFs, focus on how Microsoft, Meta and Tesla talk about AI capex and data center plans in upcoming earnings, since any shift in these budgets can quickly affect order books for hardware, software, and equipment makers.
Healthcare is up roughly 3.2% over the past week with a solid 1 year gain, and Pharmaceuticals & Biotech are even stronger on both time frames. Fresh trial news, targeted M&A like Cencora’s US$2.4b American Oncology Network deal, and specialty approvals from groups such as Edwards Lifesciences and Merck keep investors focused on drug pipelines rather than day to day consumer spending.
Portfolios that already lean on Healthcare as a stabiliser should watch upcoming US Core PCE inflation, since a stickier inflation print can extend higher rate expectations and keep demand for earnings streams that feel less tied to the economic cycle.
Consumer Discretionary & Automobiles: Short term bounce inside a tougher year
Consumer Discretionary has gained about 2.6% over seven days while still lower year to date, and Automobiles show a similar pattern, with a roughly 4.0% weekly rise against a weaker 1 year record. Stories around Tesla’s Cybercab plans, the Semi truck ramp, and QuantumScape’s battery line show ongoing product activity, but these sit against pressure from higher financing costs and cautious consumers.
If you hold retailers, autos, or travel stocks, link this sector tightly to US jobless claims and Friday’s S&P Global PMIs, because softer labor and activity data would put fresh questions around big ticket spending just as borrowing costs remain elevated.
Build Your Perfect Portfolio
With mortgage rates still above 7% and housing demand under pressure, you can stress test your income focus by starting with this list of 7 dividend fortresses
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.