
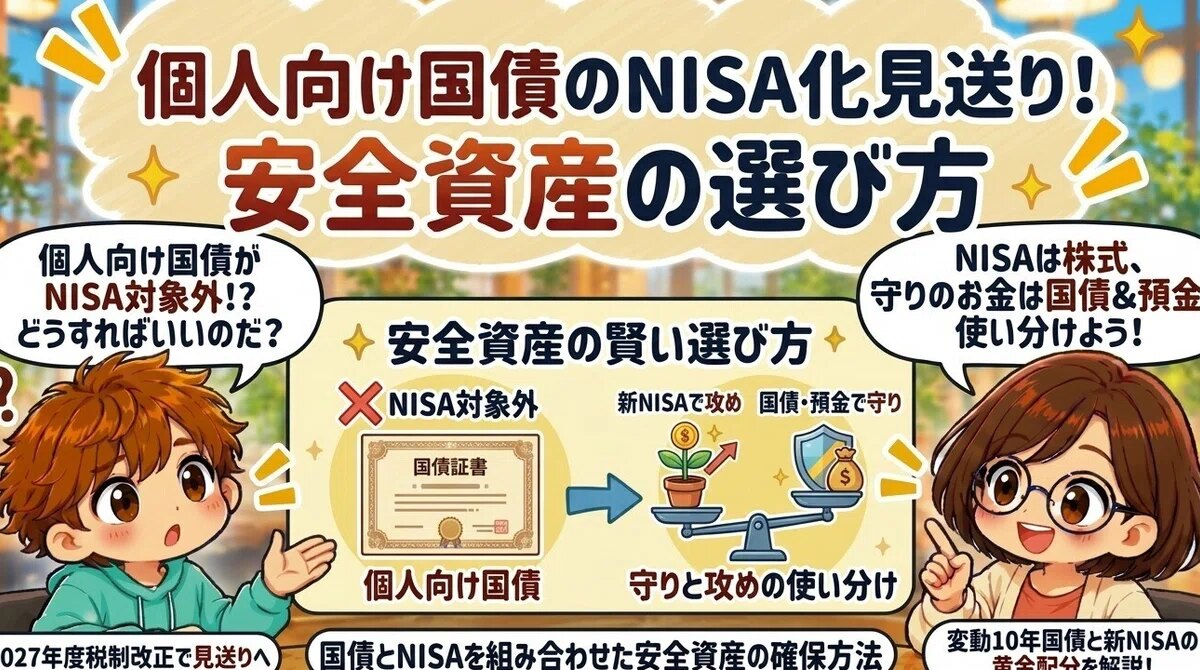
It has been revealed that the proposal to “add individual government bonds to NISA (tax-free interest and inheritance tax exemptions),” which was being considered for the fiscal year 2027 tax reform, is being adjusted to be shelved.
We will explain the points that often confuse individual investors, such as “If I can’t buy them in NISA, do individual government bonds lose their appeal?” and “What is the correct way to use deposits, government bonds, and the new NISA in an era of rising interest rates?” in an easy-to-understand 2-minute manga video.
※This video is intended for general financial and system explanation based on news reports and public documents. Please check official announcements for the final details of the tax reform. Voice provided by VOICEVOX: Shikoku Metan, Zundamon.
Key Points of This Video
-
Proposal to include individual government bonds in NISA to be shelved: Due to concerns about deposit outflows from banks and arguments that “principal-guaranteed products do not fit the original purpose of NISA, which is to promote risk investment,” the addition to NISA is expected to be shelved.
-
The ‘Floating 10-Year’ bond remains an excellent safe asset even in a taxable account: The ‘Floating 10-Year’ bond, where the government guarantees principal and interest and the applicable interest rate is reviewed every six months, remains highly attractive as a defensive asset in a rising interest rate environment, even after the approximately 20.315% tax on interest.
-
The golden rule is to prioritize stock indices in your NISA quota: Since the tax-free benefit is maximized when used for “assets with high expected returns (capital gains),” the standard approach is to allocate your NISA quota to stock mutual funds like All Country (Orkan) or the S&P 500.
-
Rules for using safe assets: Manage your assets by separating their roles: use high-interest savings accounts at online banks for immediate living defense funds (6 months to 1 year worth), and use individual government bonds for surplus funds you don’t plan to use for over a year.
Sources
-
Ministry of Finance “Individual Government Bonds Portal Page”
-
Financial Services Agency “NISA Special Website”
-
Press materials regarding the fiscal year 2027 tax reform
#IndividualGovernmentBonds #NewNISA #TaxReform #RisingInterestRates #SafeAssets #AssetAllocation #Floating10Year #Orkan #MoneyEducation #LearnWithManga